With only a modest sum in registered capital, Tianxiaxian has leveraged hundreds of millions in funding, pragmatically breaking into the warehouse sorting sector while confronting mass-production and overseas expansion challenges.
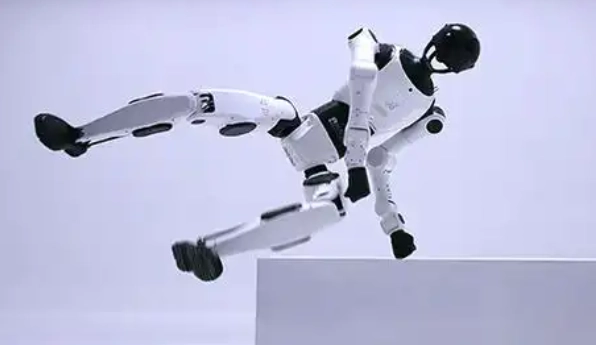
When "Tiangong Robot," which focuses on the warehousing and logistics sorting track, announced the completion of a new funding round of several hundred million yuan led by Chuxin Fund, with participation from Matrix Partners China, Hefei state-owned capital, and others, the first cognitive fluctuation in the capital market is often to confuse it with "Tiangong Ultra," which frequently appears on official stages under the Beijing Humanoid Robot Innovation Center. However, once one sees through the market illusion created by this same-name halo and examines its miniature registered capital base, which increased to only 1.4331 million yuan in April of this year, it becomes clear: this is by no means a strategic tour by a national-level scientific research team in general-purpose bipedal embodied intelligence, but rather a vertical-track startup that has been grinding away at non-standard heavy-load sorting conditions since its founding. In the cold cycle of extremely intense involution in domestic warehouse automation and e-commerce express capital expenditure hitting the brakes, it is a pragmatic breakout that uses hard tech and state-owned capital leverage to exchange for mass-production ammunition.
Over the past two years, as embodied intelligence was hyped to the skies, the vast majority of humanoid robot startups were keen to show off performative actions such as somersaults, adaptive gait, or coffee-making in showrooms and short videos. However, divorced from closed-loop validation in real industrial scenarios, general-purpose robots lacking a clear return on investment (ROI) are highly prone to falling into a suffocating state of commercialization cutoff when facing a downturn in the primary market.
By contrast, goods sorting, depalletizing and palletizing, and handling of irregular items in e-commerce and logistics supply chains, although the environment is harsh and the requirements for gripper end-effector wear resistance and visual recognition fault tolerance are demanding, constitute a "labor-replacement ledger" whose accounting logic is extremely simple and brutal. As long as the comprehensive depreciation and maintenance costs of a single unit over two to three years can break through the rigid expenditure of three-shift manual labor, enterprise customers will pay real money to buy it.
Equity Foundation and Financing Trajectory
Following the underlying thread of commercial registration and capital entry and exit to penetrate this robot company's transformation trajectory, its highly concentrated equity foundation is clearly traceable in Tianyancha records. Tianyancha business registration data shows that the operating entity, Beijing Tianxiaxian Zhichuang Robot Technology Co., Ltd., was established in 2022, with Xiao Jun as its legal representative, and its current registered capital is only about 1.4331 million yuan.
In the financing history recorded by Tianyancha, the company swiftly secured an angel round of financing as high as 200 million yuan in July of the year it was founded, attracting first-tier USD and dual-currency institutions such as Matrix Partners China and China Renaissance New Economy Fund. In April of this year, its registered capital had just been slightly raised from 1.3699 million yuan to 1.4331 million yuan, reserving a precise equity maneuvering interface for subsequent institutions to enter.
A registered capital of just over one million yuan and two rounds of cumulative financing totaling hundreds of millions of yuan create a geometric gap full of tension.
This typical "small equity, high premium" structure intuitively reflects early hard-tech institutions' extreme optimism about the team's capabilities in logistics automation algorithms and specific hardware integration. Founder Xiao Jun previously spent a long time working on the front lines of logistics technology equipment and has extremely keen engineering intuition for the physical pain points of sorting centers during Double Eleven or major promotional surges. The fundamental reason Tianxiaxian chose to strengthen the phrase "humanoid-based sorting robot" in its brand context is essentially a highly seasoned commercial compromise strategy: it borrows the valuation premium of the current embodied intelligence and humanoid concepts in the capital market, while firmly limiting its physical form for deployment to the closed scenario of warehouse sorting, which has extremely high certainty, avoiding the pointless consumption of R&D funds on bipedal walking balance algorithms on empty flat ground.
The Life-or-Death Track of Mass Production and Industry Reality
However, the entry of Hefei state-owned capital and the injection of several hundred million yuan in real money have also pushed this startup onto a life-or-death track where it must deliver industrialized mass production.
Pouring money into "expanding the mass production scale of sorting robots" and "expanding overseas markets" is backed by extremely brutal industry realities. In the domestic market, leading logistics giants such as SF Express, JD Logistics, and the Tongda group, after experiencing several years of surging capital expenditure, are now generally in a tightening cycle of contracting non-core fixed asset investment and pushing external equipment unit prices to the limit.
Traditional AGVs and cross-belt sorters have long been locked in a red ocean. Even if robotic arms or humanoid upper-body sorting machines equipped with visual large-model recognition capabilities are introduced, if they cannot achieve a crushing advantage several times over that of traditional specialized machines in units per hour (UPH) and cargo damage rate, domestic logistics giants will find it very difficult to shell out large sums themselves to replace existing mature production lines.
Overseas Expansion and the Cash Flow Black Hole of Non-Standard Customization
A deeper real challenge lies in overseas expansion and the cash flow black hole of non-standard customization.
Mature overseas markets (such as Europe, the United States, and the Middle East) have high logistics and warehousing labor costs, which indeed provides highly attractive gross margin space for domestic automation equipment going overseas. But cross-border industrial-grade delivery is a tough battle involving heavy assets and heavy overseas operations and maintenance. From engineering adaptation for different local carton packaging specifications and safety standards, to strict scrutiny by local warehouse labor unions, to the establishment of spare parts warehouses and on-site engineer teams thousands of kilometers away, every link will rapidly dilute the book reserves of financing.
If several hundred million yuan in funds cannot quickly establish a positive cycle overseas from prototype trial use to batch payment collection, the lengthy cross-border acceptance cycle is enough to drag down a young entity's precious liquidity.
In addition, sharing the same name as the officially backed "Tiangong" may bring intangible communication dividends in the early stage, but when the company moves toward large-scale commercialization and subsequent capital market filings, the exclusivity of the trade name in the intellectual property dimension and confusion in public perception will also become legal hurdles that management must clarify.
Industrial Law
This heavy bet of several hundred million yuan in early autumn conveys the soberest industrial law to the entire pan-embodied intelligence and logistics automation sector: as the capital bubble in general-purpose humanoids begins to recede, the window for exchanging valuations purely through algorithmic showmanship is closing at an accelerating pace. Only those technical tough guys who dare to insert robotic arms into the dirtiest and most exhausting sorting lines, use an extremely restrained miniature equity base to leverage industrial capital to share risks, and calculate equipment depreciation and investment payback periods down to every cent for warehouse managers can truly carve out a way to survive in this reshuffling period as the industry moves from concept hype to industrial death-match.