Mixue Bingcheng supports 60,000 stores with 880 insured employees, building a B2B empire through supply chain and digital licenses, but growth ceiling has emerged.
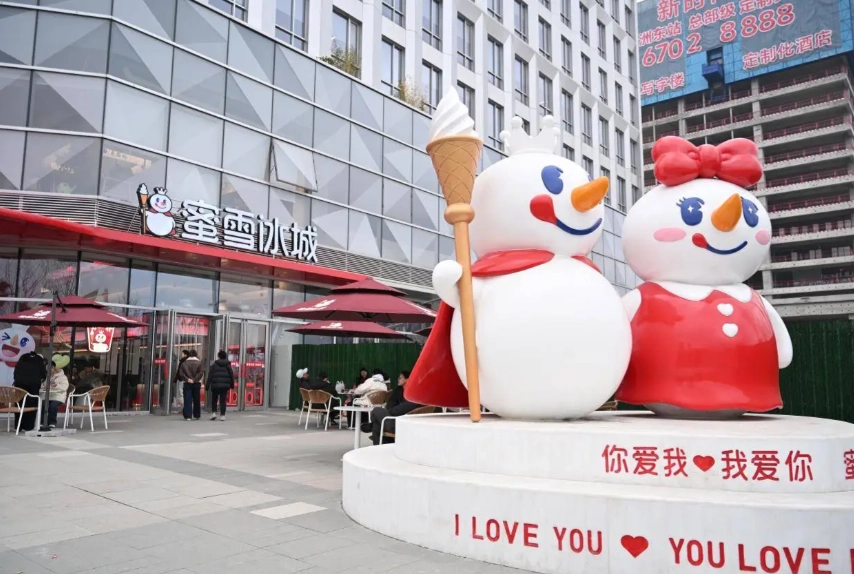
When the eye pierces through the frenzy of more than 60,000 red-and-white signs that Mixue Bingcheng has raised across the country and even overseas, and then lands back on its parent entity's industrial and commercial registration files, the most striking business contrast stands out starkly: behind this freshly made tea beverage super-empire with the highest global store density and hundreds of billions of yuan in annual revenue, the number of insured employees at its most core domestic legal entity under the latest annual report scope is actually only 880.
The registered capital of 360 million yuan and the paid-in amount of about 102 million yuan form a book difference of nearly three times, and what is even more remarkable is the cross-industry puzzle assembled by its business scope—from traditional food sales and catering services, spanning to brand management and advertising design, and then extending all the way to second-category value-added telecommunications services, single-purpose commercial prepaid card agency sales, and internet sales.
If one regards it merely as a milk tea chain selling four-yuan lemonade, then one has completely misread the true commercial essence of Snow King: this central hub supported by 880 people is by no means traditional restaurant store supervision in the conventional sense, but a massive supply chain transit mother port integrating franchise settlement, self-operated e-commerce traffic distribution, and a digital financial prepaid closed loop.
Profit Logic: Not Catering Retail, but a B2B Supply Chain Group
For a long time, the public and early-stage investors have had a widespread cognitive bias about the profit logic of new tea beverage companies, mistakenly believing that Mixue Bingcheng earns the small change spread from consumers' cups of lemonade and ice cream cones. However, once this low-ticket business falls into a purely direct-operated store model, it would long ago have been dragged down by expensive store rents, employee social insurance, and depreciation of water and electricity.The underlying logic of why Mixue Bingcheng has been able to weather cycles and polish out astonishing profit margins is that it has never been a "catering retail company," but a "B2B supply chain logistics and industrial manufacturing group" draped in the cloak of the Snow King IP.
Franchisees at the terminal are not the company's employees, but the company's most loyal long-term procurement customers; the essence of tens of thousands of stores nationwide is Snow King's distributed offline pickup warehouses for self-built factories and self-produced sugar, milk tea, fruit, and packaging materials.
Industrial and Commercial Foundation: Centralized Characteristics of 360 Million Yuan Registered Capital and 880 Insured Employees
Following the traces left at the underlying commercial level to penetrate the organizational structure of this massive entity, its asset foundation in Tianyancha files displays highly tense centralized characteristics. Tianyancha industrial and commercial data show that Mixue Bingcheng Co., Ltd. was established on April 30, 2008, with Zhang Hongfu as the legal representative, registered capital of 360 million yuan, paid-in capital of about 102 million yuan, and registration status of surviving.
Among the enterprise types penetrated by Tianyancha, it is registered as "other joint-stock company (unlisted)," and the number of insured employees under the 2025 annual report scope is 880.After 18 years of continuous operation, the structure in which paid-in capital accounts for about 28% of registered capital reflects meticulous design during the early joint-stock restructuring and the establishment of the equity incentive platform.
The insured scale of 880 people forms an extremely悬殊 geometric gap with the hundreds of thousands of terminal employees nationwide.
This precisely confirms its ultimate lightweight and outsourcing isolation strategy in organizational structure. Data accumulated by Tianyancha indicate that these 880 core personnel receiving parent-entity salaries and social insurance are mainly composed of IT algorithm engineers in the national dispatch room, supply chain logistics scheduling experts, core brand marketing operators, and the legal compliance team. Massive warehousing and sorting, trunk-line cold-chain logistics transportation, and upstream raw material processing (such as professional entities like Daka International) are all exquisitely cut into independent subsidiaries or third-party professional carriers in various locations;
while the millions of frontline beverage-making employees at tens of thousands of stores have their employment risks fully borne by individual industrial and commercial households or regional franchisees.This lightweight parent-entity design firmly blocks heavy-asset frictions such as labor law compliance, work-related injury social insurance, and store accidents outside the core hub.
Cross-Industry Qualifications: The Legal Foundation of the Digital Flywheel
An even more intriguing deep secret lies hidden in its unusually cross-industry combination of qualifications.
The business scope disclosed by Tianyancha shows that, in addition to conventional catering and food sales, this entity simultaneously holds a full set of hardcore licenses for "second-category value-added telecommunications services," "single-purpose commercial prepaid card agency sales," and "internet sales." This seemingly unrelated qualification puzzle precisely completes the legal foundation of its super private-domain flywheel:
First, "second-category value-added telecommunications services" and "internet sales" directly lock down the data compliance hub of its self-operated ordering mini-programs and online malls for hundreds of millions of members. When consumers order through mobile phones or buy Snow King merchandise, all traffic, user profiles, and digital transaction data are deposited within the parent entity system, avoiding third-party delivery platforms' bottleneck interception of member assets.
Second, the "single-purpose commercial prepaid card agency sales" license is the core weapon for operating its astonishingly large interest-free cash flow pool. When consumers top up at stores nationwide with "deposit 100, get 10 free," purchase gift cards, or enterprises purchase gift vouchers in bulk, the massive capital pool achieves compliant collection and deposition at the parent-entity level. With the support of extremely low capital costs, the parent entity not only holds abundant low-interest float funds, but can also firmly constrain franchisees' performance behavior in reverse through unified prepaid settlement.
Growth Ceiling: Store Internal Friction and Quality Control Crisis
However, once the outer garment of this exquisite supply chain and digital capital machine is pulled back, the hidden growth ceiling and cyclical backlash are already approaching.
As the total number of stores worldwide approaches the 60,000 mark, county towns and township streets in the domestic lower-tier market have long been filled with dense red-and-white stores, and per-store foot traffic and average daily cup output face extremely severe internal cannibalization and stampede.When the marginal benefits of newly opened franchise stores diminish, and franchisees' closure rates and payback periods begin to lengthen, the flywheel that originally relied on continuously selling raw materials, ice cream machines, and packaging materials will encounter a braking of its rotation speed.
A deeper crisis occurs on the tightrope of quality control and food safety.
Under this lightweight headquarters model disclosed by Tianyancha, 880 central employees must supervise cold-chain freshness preservation and daily operating standards across dozens of countries and more than 60,000 physical nodes, which is almost a human engineering game with an extremely low win rate. Franchisee violations such as overnight lemon slices and altered shelf-life labels remain repeatedly prohibited, and every loss of control at an individual store will directly strike the brand reputation of the Snow King parent entity through internet public opinion.
When the low-price mindset is bombarded by major competitors with suicidal promotions of "nine yuan and nine, or even five yuan," the absolute cost-performance moat on which Mixue Bingcheng built its rise is being gradually flattened by peers' cost-ignoring involution.
Endgame Logic: Crossing from Rampant Store Opening to Refined Retention
This 360 million yuan industrial and commercial foundation polished over 18 years releases the clearest business logic to the entire Chinese consumer chain and franchise camp: the endgame of fast-moving consumer franchise is not to be the head chef, but to be the logistics warehouse manager and tax dispatch officer beside the money-printing machine. Leveraging tens of thousands of nodes with a core establishment of fewer than a thousand people demonstrates modern business's ultimate use of light-asset collaborative leverage.
But when the store-opening dividend of physical space is completely squeezed dry and tens of thousands of franchisees struggle bitterly in a stock-market sea of blood, this freshly made tea beverage overlord armed to the teeth with supply chain and digital licenses will ultimately have to face the ultimate test of crossing from rampant store opening to refined retention in the game of how to ensure franchisees do not lose money while maintaining high profits in its own supply chain.